HOME SALES UP.... INVENTORY DOWN!
Florida's existing home sales rose 24 percent in January, making it the fifth month in a row that sales activity increased year-to-year, according to the latest housing data from FAR. Florida Realtors also reported a 13 percent gain in statewide sales of existing condos last month. NAR reported that nationwide sales of existing homes - all housing types - fell 5.3 percent last month; at the same time, inventories fell to a two-year low.
Wednesday, February 25, 2009


Friday, February 20, 2009
Are You Still Waiting For The Government?
Article provided by Michael Payette at M&I Bank.
During the first quarter of 2009, the first 100 days of the new President's term, you are no doubt going to hear a lot of news stories about the economic stimulus plan and the financial rescue package and their possible ramifications to the real estate and mortgage markets.
You're going to see headlines about new incentives for home buyers and hear stories about 4% interest rates. But the truth is that right now, at the time of the writing of this article, the government already has in place one of the largest tax incentives for qualifying home buyers it has ever offered - up to an $8,000 tax credit for first-time buyers, and mortgage rates are within a half a point of being the lowest they've been in our country's history.
The truth is that, while all of this is great news for those looking to buy or refinance a home in 2009, none of it matters if you can't qualify for financing. None of it matters if you sit on the fence and watch the great opportunity of homeownership pass you by.
Make sure your financial house is in order
If the idea of buying or refinancing a home in 2009 has even crossed your mind, give us a call. We'll review your financial situation and see what makes sense for your individual goals. Remember, because of increased delinquencies and today's tougher economy, lenders have tightened standards for both new purchases and refis. And while mortgage financing is certainly available and affordable to everyone who qualifies, you're going to need a solid credit score, you'll need to be able to document your income, and, if you're purchasing a new home without a special government program from the VA or USDA, you're likely going to need a down payment as well – at least 3.5% for an FHA loan. And there's no stimulus bill or bail-out plan that is going to change this. So, if you're looking to purchase a new home in 2009, take the time to locate the following items:
Your W-2s and tax returns for the last two years;
Your last three months of bank statements; and
Pay-stubs for the most recent 30 days.
If you haven't checked your credit in awhile, now is the time to do so. A lot could have changed since the last time you checked it, good or bad, and you don't want any surprises that might alter your plans. We'll gladly review your credit for you and see if there is anything that needs to be addressed, but don't wait. It would be a shame to miss out on a great opportunity simply because you didn't check your credit report.
For homeowners with enough equity to refinance, now may be the time to lock in a low rate. Sure rates could go lower, even to the 4% level you've heard about in the news. But rates could just as easily start to rise again, and home values could drop even lower, making it difficult for your house to appraise. In the financial and credit markets, there are no guarantees, and there's nothing in the stimulus bill or bail-out plan to address mortgage rates. Why lose money waiting around for an opportunity to save a little bit more each month in the future when you can have significant savings every month right now?
Let us review your mortgage and see if you can benefit. The worst thing that could happen is you find out that you already have the best mortgage and interest rate possible.
For more information, please email Michael Payette at M&I Bank, michael.payette@micorp.com or phone him at (813)334-8412. Mention you saw this article on my blog, if you would.
During the first quarter of 2009, the first 100 days of the new President's term, you are no doubt going to hear a lot of news stories about the economic stimulus plan and the financial rescue package and their possible ramifications to the real estate and mortgage markets.
You're going to see headlines about new incentives for home buyers and hear stories about 4% interest rates. But the truth is that right now, at the time of the writing of this article, the government already has in place one of the largest tax incentives for qualifying home buyers it has ever offered - up to an $8,000 tax credit for first-time buyers, and mortgage rates are within a half a point of being the lowest they've been in our country's history.
The truth is that, while all of this is great news for those looking to buy or refinance a home in 2009, none of it matters if you can't qualify for financing. None of it matters if you sit on the fence and watch the great opportunity of homeownership pass you by.
Make sure your financial house is in order
If the idea of buying or refinancing a home in 2009 has even crossed your mind, give us a call. We'll review your financial situation and see what makes sense for your individual goals. Remember, because of increased delinquencies and today's tougher economy, lenders have tightened standards for both new purchases and refis. And while mortgage financing is certainly available and affordable to everyone who qualifies, you're going to need a solid credit score, you'll need to be able to document your income, and, if you're purchasing a new home without a special government program from the VA or USDA, you're likely going to need a down payment as well – at least 3.5% for an FHA loan. And there's no stimulus bill or bail-out plan that is going to change this. So, if you're looking to purchase a new home in 2009, take the time to locate the following items:
Your W-2s and tax returns for the last two years;
Your last three months of bank statements; and
Pay-stubs for the most recent 30 days.
If you haven't checked your credit in awhile, now is the time to do so. A lot could have changed since the last time you checked it, good or bad, and you don't want any surprises that might alter your plans. We'll gladly review your credit for you and see if there is anything that needs to be addressed, but don't wait. It would be a shame to miss out on a great opportunity simply because you didn't check your credit report.
For homeowners with enough equity to refinance, now may be the time to lock in a low rate. Sure rates could go lower, even to the 4% level you've heard about in the news. But rates could just as easily start to rise again, and home values could drop even lower, making it difficult for your house to appraise. In the financial and credit markets, there are no guarantees, and there's nothing in the stimulus bill or bail-out plan to address mortgage rates. Why lose money waiting around for an opportunity to save a little bit more each month in the future when you can have significant savings every month right now?
Let us review your mortgage and see if you can benefit. The worst thing that could happen is you find out that you already have the best mortgage and interest rate possible.
For more information, please email Michael Payette at M&I Bank, michael.payette@micorp.com or phone him at (813)334-8412. Mention you saw this article on my blog, if you would.
Thursday, February 19, 2009
Home Buyer Credit
CREDIT WHERE CREDIT IS DUE
First-time homebuyers have exactly 285 days to buy a home if they want to pocket $8,000 tax-free. It's not long. Every homebuyer has unique circumstances, however, and specific questions. The National Association of Home Builders (NAHB) has launched a consumer Web site with detailed information and an extensive list of frequently-asked questions. The homebuyer resource is found at: www.federalhousingtaxcredit.com
© Copyright 2009 INFORMATION, INC. Bethesda, MD
First-time homebuyers have exactly 285 days to buy a home if they want to pocket $8,000 tax-free. It's not long. Every homebuyer has unique circumstances, however, and specific questions. The National Association of Home Builders (NAHB) has launched a consumer Web site with detailed information and an extensive list of frequently-asked questions. The homebuyer resource is found at: www.federalhousingtaxcredit.com
© Copyright 2009 INFORMATION, INC. Bethesda, MD
Wednesday, February 18, 2009

Monday, February 16, 2009
NAR: Implement Stimulus Package Quickly!
WASHINGTON – Feb. 16, 2009 –
Now that the American Recovery and Reinvestment Act has been sent to President Obama for his signature, the National Association of Realtors® (NAR) looks forward to swift implementation.
“We are pleased that Congress and the administration have taken prompt action to address the current economic crisis,” says NAR President Charles McMillan. “Job creation and tax cuts are going to help families recover and prosper, and these initiatives will help more people keep their homes and help others become homeowners.”
The legislation contains two important housing provisions advocated by NAR. The final stimulus bill increases the first-time homebuyer tax credit to $8,000 and eliminates the repayment requirement of earlier legislation. In addition, the credit availability has been extended until Dec. 1, 2009.
“These important provisions will help bring first-time homebuyers to the market and reduce housing inventory,” says McMillan. NAR estimates that the homebuyer tax provisions could stimulate up to 300,000 additional home sales, helping stabilize home values and potentially preventing some homeowners from being “underwater” on their mortgage, which can often lead to foreclosure.
The bill also reinstates the 2008 higher loan limits for FHA, Fannie Mae and Freddie Mac. “These … make mortgages affordable regardless of where you live,” McMillan says. “ This will also help reduce inventory and improve liquidity in the overall mortgage market.”
NAR commended President Obama and Congress for including neighborhood stabilization efforts to help communities purchase and rehabilitate foreclosed and vacant properties. Realtors also praised the provision to help America’s wounded soldiers who need to move or relocate.
In addition to federal bailout measures, NAR’s also advocates better foreclosure mitigation efforts and lower interest rates for homeowners and buyers. NAR expects these components to be addressed in the coming days.
© 2009 FLORIDA ASSOCIATION OF REALTORS®
Now that the American Recovery and Reinvestment Act has been sent to President Obama for his signature, the National Association of Realtors® (NAR) looks forward to swift implementation.
“We are pleased that Congress and the administration have taken prompt action to address the current economic crisis,” says NAR President Charles McMillan. “Job creation and tax cuts are going to help families recover and prosper, and these initiatives will help more people keep their homes and help others become homeowners.”
The legislation contains two important housing provisions advocated by NAR. The final stimulus bill increases the first-time homebuyer tax credit to $8,000 and eliminates the repayment requirement of earlier legislation. In addition, the credit availability has been extended until Dec. 1, 2009.
“These important provisions will help bring first-time homebuyers to the market and reduce housing inventory,” says McMillan. NAR estimates that the homebuyer tax provisions could stimulate up to 300,000 additional home sales, helping stabilize home values and potentially preventing some homeowners from being “underwater” on their mortgage, which can often lead to foreclosure.
The bill also reinstates the 2008 higher loan limits for FHA, Fannie Mae and Freddie Mac. “These … make mortgages affordable regardless of where you live,” McMillan says. “ This will also help reduce inventory and improve liquidity in the overall mortgage market.”
NAR commended President Obama and Congress for including neighborhood stabilization efforts to help communities purchase and rehabilitate foreclosed and vacant properties. Realtors also praised the provision to help America’s wounded soldiers who need to move or relocate.
In addition to federal bailout measures, NAR’s also advocates better foreclosure mitigation efforts and lower interest rates for homeowners and buyers. NAR expects these components to be addressed in the coming days.
© 2009 FLORIDA ASSOCIATION OF REALTORS®
Friday, February 13, 2009
Big Banks Announce Foreclosure Halt!
Big Banks Announce Foreclosure Halt
By ALAN ZIBEL,
AP
WASHINGTON (Feb. 13) — JPMorgan Chase & Co. and Citigroup Inc. are halting home foreclosures while the Obama administration develops its plans to help the U.S. housing market.
Skip over this content
JPMorgan Chief Executive Jamie Dimon said the New York company plans to halt new foreclosures for owner-occupied home loans through March 6. Dimon made the pledge in a letter to Rep. Barney Frank, D-Mass., chairman of the House Financial Services Committee, who released it on Friday.
Citigroup's foreclosure moratorium applies to all "Citi owned first mortgage loans that are the principal residence of the customer as well as all loans Citi services where we have reached an understanding with the investor" until President Barack Obama's administration has finalized the details of the loan modification program or March 12, whichever is earlier, according to a company release. New York-based Citi's action expands on a similar effort that it started in November.
Frank earlier this week called on the mortgage industry to enact such broad foreclosure moratoriums.
The administration is working on a plan to spend $50 billion on foreclosure prevention and establish national standards for modifying home loans.
"We stand ready to work with you to put the appropriate processes in place, including a national modification standard, to reduce the incidence of foreclosure and to encourage long-term, sustainable home mortgages," Dimon wrote.
Government-controlled mortgage finance companies Fannie Mae and Freddie Mac suspended foreclosure sales during the winter holidays and have halted evictions from foreclosed properties until next month. And earlier this week, John Reich, director of the Office of Thrift Supervision, urged the more than 800 thrift institutions nationwide to do the same.
Meanwhile, the administration is considering spending taxpayer dollars to cut monthly payments for homeowners on the verge of foreclosure.
Still, deciding who would qualify would be a challenge, especially as foreclosures continue to soar. More than 274,000 U.S. households received at least one foreclosure-related notice last month, according to RealtyTrac Inc.
The administration also is expected to back a push in Congress — but opposed by the mortgage industry — to let bankruptcy judges alter the terms of primary home loans. Earlier this week, Obama said it "makes no sense" that judges are not allowed to do so. The mortgage industry argues that this prohibition allows lenders to charge lower rates.
Copyright 2009 The Associated Press.
By ALAN ZIBEL,
AP
WASHINGTON (Feb. 13) — JPMorgan Chase & Co. and Citigroup Inc. are halting home foreclosures while the Obama administration develops its plans to help the U.S. housing market.
Skip over this content
JPMorgan Chief Executive Jamie Dimon said the New York company plans to halt new foreclosures for owner-occupied home loans through March 6. Dimon made the pledge in a letter to Rep. Barney Frank, D-Mass., chairman of the House Financial Services Committee, who released it on Friday.
Citigroup's foreclosure moratorium applies to all "Citi owned first mortgage loans that are the principal residence of the customer as well as all loans Citi services where we have reached an understanding with the investor" until President Barack Obama's administration has finalized the details of the loan modification program or March 12, whichever is earlier, according to a company release. New York-based Citi's action expands on a similar effort that it started in November.
Frank earlier this week called on the mortgage industry to enact such broad foreclosure moratoriums.
The administration is working on a plan to spend $50 billion on foreclosure prevention and establish national standards for modifying home loans.
"We stand ready to work with you to put the appropriate processes in place, including a national modification standard, to reduce the incidence of foreclosure and to encourage long-term, sustainable home mortgages," Dimon wrote.
Government-controlled mortgage finance companies Fannie Mae and Freddie Mac suspended foreclosure sales during the winter holidays and have halted evictions from foreclosed properties until next month. And earlier this week, John Reich, director of the Office of Thrift Supervision, urged the more than 800 thrift institutions nationwide to do the same.
Meanwhile, the administration is considering spending taxpayer dollars to cut monthly payments for homeowners on the verge of foreclosure.
Still, deciding who would qualify would be a challenge, especially as foreclosures continue to soar. More than 274,000 U.S. households received at least one foreclosure-related notice last month, according to RealtyTrac Inc.
The administration also is expected to back a push in Congress — but opposed by the mortgage industry — to let bankruptcy judges alter the terms of primary home loans. Earlier this week, Obama said it "makes no sense" that judges are not allowed to do so. The mortgage industry argues that this prohibition allows lenders to charge lower rates.
Copyright 2009 The Associated Press.
Thursday, February 12, 2009
Florida’s existing home, condo sales rise in 4Q 2008
ORLANDO, Fla. – Feb. 12, 2009 –
Sales of existing single-family homes in Florida rose 13 percent in fourth quarter 2008 compared to the same period a year earlier, according to the latest housing statistics from the Florida Association of Realtors® (FAR). A total of 30,163 existing homes sold statewide in 4Q 2008; during the same period the year before, a total of 26,635 existing homes sold statewide. It marks the second consecutive quarter that Florida has reported higher existing home sales; sales activity rose 5 percent in 3Q 2008 compared to the same period the previous year, according to FAR.
Florida Realtors also reported a 3 percent gain in statewide sales of existing condominiums in the fourth quarter compared to the same time the previous year. This marks the first three-month period that has noted increased statewide sales in both the existing home and condo markets compared to year-ago levels.
Twelve of Florida’s metropolitan statistical areas (MSAs) reported increased sales of existing homes in the fourth quarter compared to the same three-month-period a year earlier, while eight MSAs showed gains in condo sales. A growing number of local markets have reported increased sales activity over the past few months, according to FAR.
The statewide existing-home median sales price was $161,200 in the fourth quarter; a year earlier, it was $216,600 for a decrease of 26 percent. According to industry analysts with the National Association of Realtors® (NAR), there remains a significant downward distortion in the current median price due to many discounted sales, including a large number of foreclosures. The median is a typical market price where half the homes sold for more, half for less.
To gain insight into current trends in Florida’s real estate industry, the University of Florida’s Bergstrom Center for Real Estate Studies conducts a quarterly survey of industry executives, market research economists, real estate scholars and other experts. According to the fourth quarter 2008 survey, respondents’ increasing concerns about the economy have dampened the investment outlook for various types of properties.
However, one positive sign is the recent dramatic increase in refinancing with the availability of 5 percent mortgage rates in mid-December, according to Dr. Wayne Archer, center director. If additional programs are put into place that create 4.5 percent Federal Housing Administration mortgages for people who have difficulty making payments, he said, it will do even more to stabilize the housing industry.
In the year-to-year quarterly comparison for condo sales, 8,374 units sold statewide for the quarter compared to 8,098 in 4Q 2007 for a 3 percent increase. The statewide existing-condo median sales price was $136,400 for the three-month period; in 4Q 2007, it was $190,400 for a decrease of 28 percent.
Continuing low mortgage rates remain another favorable influence on the housing sector. According to Freddie Mac, the national commitment rate for a 30-year conventional fixed-rate mortgage averaged 5.86 percent in 4Q 2008; one year earlier, it averaged 6.23 percent.
The outlook for housing and the economy remains clouded despite improved affordability conditions, according to NAR’s latest industry forecast. “For a sustainable housing market recovery and, thus a sustainable economic recovery, we need a significant housing stimulus and mortgage availability for qualified borrowers,” said NAR Chief Economist Lawrence Yun.
© 2009 FLORIDA ASSOCIATION OF REALTORS
Sales of existing single-family homes in Florida rose 13 percent in fourth quarter 2008 compared to the same period a year earlier, according to the latest housing statistics from the Florida Association of Realtors® (FAR). A total of 30,163 existing homes sold statewide in 4Q 2008; during the same period the year before, a total of 26,635 existing homes sold statewide. It marks the second consecutive quarter that Florida has reported higher existing home sales; sales activity rose 5 percent in 3Q 2008 compared to the same period the previous year, according to FAR.
Florida Realtors also reported a 3 percent gain in statewide sales of existing condominiums in the fourth quarter compared to the same time the previous year. This marks the first three-month period that has noted increased statewide sales in both the existing home and condo markets compared to year-ago levels.
Twelve of Florida’s metropolitan statistical areas (MSAs) reported increased sales of existing homes in the fourth quarter compared to the same three-month-period a year earlier, while eight MSAs showed gains in condo sales. A growing number of local markets have reported increased sales activity over the past few months, according to FAR.
The statewide existing-home median sales price was $161,200 in the fourth quarter; a year earlier, it was $216,600 for a decrease of 26 percent. According to industry analysts with the National Association of Realtors® (NAR), there remains a significant downward distortion in the current median price due to many discounted sales, including a large number of foreclosures. The median is a typical market price where half the homes sold for more, half for less.
To gain insight into current trends in Florida’s real estate industry, the University of Florida’s Bergstrom Center for Real Estate Studies conducts a quarterly survey of industry executives, market research economists, real estate scholars and other experts. According to the fourth quarter 2008 survey, respondents’ increasing concerns about the economy have dampened the investment outlook for various types of properties.
However, one positive sign is the recent dramatic increase in refinancing with the availability of 5 percent mortgage rates in mid-December, according to Dr. Wayne Archer, center director. If additional programs are put into place that create 4.5 percent Federal Housing Administration mortgages for people who have difficulty making payments, he said, it will do even more to stabilize the housing industry.
In the year-to-year quarterly comparison for condo sales, 8,374 units sold statewide for the quarter compared to 8,098 in 4Q 2007 for a 3 percent increase. The statewide existing-condo median sales price was $136,400 for the three-month period; in 4Q 2007, it was $190,400 for a decrease of 28 percent.
Continuing low mortgage rates remain another favorable influence on the housing sector. According to Freddie Mac, the national commitment rate for a 30-year conventional fixed-rate mortgage averaged 5.86 percent in 4Q 2008; one year earlier, it averaged 6.23 percent.
The outlook for housing and the economy remains clouded despite improved affordability conditions, according to NAR’s latest industry forecast. “For a sustainable housing market recovery and, thus a sustainable economic recovery, we need a significant housing stimulus and mortgage availability for qualified borrowers,” said NAR Chief Economist Lawrence Yun.
© 2009 FLORIDA ASSOCIATION OF REALTORS
Wednesday, February 11, 2009
FICO '08 System For Creditworthiness
A new system for determining your credit-worthiness, FICO '08, rolls out this Thursday, and there's nothing you can to do stop it.
1. Spouses and children can improve their credit score by being an authorized user on a credit card account, but that's it. No more piggybacking off strangers.
2. Debts less than $100 that go to collections will matter less.
3. They will look at the total picture more. A single repossession, for instance, won't matter as much if everything else looks good.
4. Having less available credit will drag down your score more.
5. Diversity matters more. A mix of healthy auto, personal and student loans would bring up a score.
6. Closing accounts will bring down the score.
1. Spouses and children can improve their credit score by being an authorized user on a credit card account, but that's it. No more piggybacking off strangers.
2. Debts less than $100 that go to collections will matter less.
3. They will look at the total picture more. A single repossession, for instance, won't matter as much if everything else looks good.
4. Having less available credit will drag down your score more.
5. Diversity matters more. A mix of healthy auto, personal and student loans would bring up a score.
6. Closing accounts will bring down the score.
Property Taxes Down Last Two Years!
TALLAHASSEE, Fla. (AP) – Feb. 11, 2009 –
A pair of tax-relief measures passed in the last two years have helped reduce property taxes for Floridians after three decades of steady increases, according to reports presented Tuesday in the state Senate.
Senate and Department of Revenue staffers told the Senate Finance and Tax Committee that non-school property tax collections dropped 2.1 percent in 2007 after the Legislature ordered a tax rate rollback. Then they dropped 3.8 percent in 2008 after voters approved a tax-cutting constitutional amendment.Those decreases come after 32 years of average annual increases of 10 percent.
School property taxes are exempt from parts of the tax-relief measures, but they are also dropping because of declining property values across the state. That’s expected to cut school revenues by up to $1 billion in the next budget year, which begins July 1, unless lawmakers increase local school tax rates or find state dollars to replace that money.
Sen. Thad Altman, the committee’s chairman, said he was satisfied that non-school taxes have dropped but Florida’s property tax structure remains unfair. That’s due mainly to the Save Our Homes Amendment adopted in 1992. It gives tax breaks to owners of primary homes but shifts the burden to other taxpayers including recent homebuyers, businesses and owners of second and vacation homes.
Primary homeowners “who happened to buy when the market was high are paying relatively high taxes and those who bought when the market was low many, many years ago ... are paying much less,” said Altman, R-Melbourne. “We haven’t really solved the heart of the problem.”
Altman said it’s unlikely lawmakers will solve it this year, either, because that would require amending the Florida Constitution. It would take a three-fourths vote in each chamber to call a special election to amend the constitution this year but only a three-fifths vote to put an amendment on the 2010 general election ballot.
“We need to be deliberate when we amend the constitution,” Altman said. “I don’t think you’re going to see a big rush to get constitutional amendments on the ballot this year because we’re going to have another year of deliberation.”
One provision of the tax-cutting amendment voters approved in January 2009 has not panned out as expected due to the state’s housing slump and national credit crunch. It allows homeowners to take part of their Save Our Homes benefits with them when they move.
This “portability” measure had been forecast to cut taxable values by $11.6 billion last year, but the actual figure was only $3.4 billion with just 42,647 homeowners taking advantage of it.
An extra $25,000 exemption for primary homes on non-school taxes in addition to an existing $25,000 exemption on all taxes cut taxable values by $92 billion. That’s slightly more than predicted.
A new $25,000 exemption on the tax paid by businesses for equipment, furniture and other tangible personal property cut $7.9 billion in property value, about $3 billion less than forecast.
Copyright © 2009 The Associated Press, Bill Kaczor. All rights reserved
A pair of tax-relief measures passed in the last two years have helped reduce property taxes for Floridians after three decades of steady increases, according to reports presented Tuesday in the state Senate.
Senate and Department of Revenue staffers told the Senate Finance and Tax Committee that non-school property tax collections dropped 2.1 percent in 2007 after the Legislature ordered a tax rate rollback. Then they dropped 3.8 percent in 2008 after voters approved a tax-cutting constitutional amendment.Those decreases come after 32 years of average annual increases of 10 percent.
School property taxes are exempt from parts of the tax-relief measures, but they are also dropping because of declining property values across the state. That’s expected to cut school revenues by up to $1 billion in the next budget year, which begins July 1, unless lawmakers increase local school tax rates or find state dollars to replace that money.
Sen. Thad Altman, the committee’s chairman, said he was satisfied that non-school taxes have dropped but Florida’s property tax structure remains unfair. That’s due mainly to the Save Our Homes Amendment adopted in 1992. It gives tax breaks to owners of primary homes but shifts the burden to other taxpayers including recent homebuyers, businesses and owners of second and vacation homes.
Primary homeowners “who happened to buy when the market was high are paying relatively high taxes and those who bought when the market was low many, many years ago ... are paying much less,” said Altman, R-Melbourne. “We haven’t really solved the heart of the problem.”
Altman said it’s unlikely lawmakers will solve it this year, either, because that would require amending the Florida Constitution. It would take a three-fourths vote in each chamber to call a special election to amend the constitution this year but only a three-fifths vote to put an amendment on the 2010 general election ballot.
“We need to be deliberate when we amend the constitution,” Altman said. “I don’t think you’re going to see a big rush to get constitutional amendments on the ballot this year because we’re going to have another year of deliberation.”
One provision of the tax-cutting amendment voters approved in January 2009 has not panned out as expected due to the state’s housing slump and national credit crunch. It allows homeowners to take part of their Save Our Homes benefits with them when they move.
This “portability” measure had been forecast to cut taxable values by $11.6 billion last year, but the actual figure was only $3.4 billion with just 42,647 homeowners taking advantage of it.
An extra $25,000 exemption for primary homes on non-school taxes in addition to an existing $25,000 exemption on all taxes cut taxable values by $92 billion. That’s slightly more than predicted.
A new $25,000 exemption on the tax paid by businesses for equipment, furniture and other tangible personal property cut $7.9 billion in property value, about $3 billion less than forecast.
Copyright © 2009 The Associated Press, Bill Kaczor. All rights reserved
Monday, February 9, 2009
Bloomingdale Hills Pool Home!


WHAT MAKES THIS 3-BEDROOM, 2-BATH HOME SPECIAL IS BEYOND THE FRONT DOOR! Step in and look back through the inviting, spacious great room to the 300-square-foot, screened and covered lanai with spa overlooking a beautiful pool with waterspouts.All that in a home at this price? Yes, but there's even more -- starting with the custom tile floors in all living and wet areas, as well as the hardwood in bedrooms. You'll find quality from the vaulted ceilings to art niches, from the fresh exterior paint to custom exterior lighting, from the wood-burning fireplace to the new roof! It's all on a lovely corner lot with privacy fencing around the gorgeous pool, which features a attractive seating area as part of its extended deck. Last, and perhaps best, it's in Bloomingdale Hills -- a low-fee community ($160 per year) perfectly located for easy access to schools, shops, restaurants, and commuter routes. Some smart buyer will grab this one! Why not you?
Florida Strawberry Festival!

 The Florida Strawberry Festival is upon us, once again. It seems like we just finished with Gasparilla and the State Fair is still running, but in a couple of weeks, beginning February 26th and running through March 8th, The Florida Strawberry Festival will be goibng strong in Plant City. There will be plenty of strawberry short cake, rides and entertainment. Click on the Title and it will take you directly to the official web site where you can find all the information you want about the festival.
Friday, February 6, 2009
New Fish Hawk Listing!


YES, YOU REALLY CAN AFFORD FISHHAWK RANCH! Get everything the master-planned community offers by moving into Cardel-built quality on a corner lot in Meadow Park -- a small, circular street within walking distance of top-rated Bevis Elementary School! Inside 1,312 square feet, you'll find 3 bedrooms (1 lacks a closet), 2 baths, and an open design that features a great room with sliders to the back yard. The fully applianced kitchen includes raised-panel oak cabinets, a center island and a separate, windowed breakfast nook. Extra touches include volume ceilings, plant shelves, art niches, plus tile in the kitchen and bathrooms. What's more, the full 2-car garage is larger than what you'll find in rival homes at higher prices! FishHawk's community amenities include a state-of-the-art aquatic center, recreation facilities for virtually every sport from tennis to skateboarding, fitness centers, miles of wooded walking trails, a private movie theater, and a centrally located town center just a half-hour from Tampa. Don't miss this opportunity to get in here for a low price!
This is a SHORT SALE property and is listed at $109,900.
Wednesday, February 4, 2009
Florida State Fair Begins

Beginning Feb 5th thru Feb 16th Florida's Biggest Outside Funhouse is right in our own backyard at the State Fair Grounds in Tampa. It is the 105th Edition of the Florida State Fair. http://www.floridastatefair.com/
Experienced Mortgage Lender For Your Pre-Approval!
 Hello! Allow me to introduce myself: My name is Michael Payette and I've been a Mortgage Lender for 10 years. I've helped over 500 individuals and families with their financing. Excellent service is a key part of my success and, as a result, most of my business comes from repeat customers and referral sources. My team has over 120 years of combined experience, so rest assured we will take excellent care of you. M&I Bank has been around for over 160 years and is doing well even in today's tough economy. Not only do I represent M&I Bank but also several other mortgage companies. As a result I'm able to comparison shop for you and get you the best possible rate. Additionally, our fees typically run $300 to $500 less than our competitors, which is a direct savings to you. For a limited time we are offering free mortgage pre-approvals. It's free, quick and easy to do. It's important to do this to see how much you would qualify for in today's market. Call me today!
"My goal is to exceed your expectations!"
Michael Payette
Residential Lending - M&I Bank
Ph: (813) 334-8412
Fax: (813) 902-7002
email: michael.payette@micorp.com

Tuesday, February 3, 2009
Pending Home Sales Show Gain!
WASHINGTON – Feb. 3, 2009 –
Pending home sales increased as more buyers took advantage of improved affordability conditions, according to the National Association of Realtors® (NAR). Big gains in the South and Midwest offset modest declines in other regions.
The Pending Home Sales Index, a forward-looking indicator based on contracts signed in December, rose 6.3 percent to 87.7 from an upwardly revised reading of 82.5 in November, and is 2.1 percent higher than December 2007 when it was 85.9.
Lawrence Yun, NAR chief economist, says the index shows a modest rebound. “The monthly gain in pending home sales, spurred by buyers responding to lower home prices and mortgage interest rates, more than offset an index decline in the previous month,” he says. “The biggest gains were in areas with the biggest improvements in affordability.”
NAR’s Housing Affordability index rose 10.9 percent in December to 158.8, the highest on record. The HAI shows that the relationship between home prices, mortgage interest rates and family income is the most favorable since tracking began in 1970.“Significant uncertainty still clouds the housing market despite improved affordability conditions. For a sustainable housing market recovery and, hence, sustainable economic recovery, we need a significant housing stimulus and mortgage availability for qualified borrowers,” Yun added.
The PHSI in the Northeast slipped 1.7 percent to 62.1 in December and is 14.5 percent below a year ago. In the Midwest the index jumped 12.8 percent to 83.7 but remains 1.2 percent below December 2007.
The index in the South surged 13.0 percent to 96.8 in December and is 1.6 percent above a year ago. In the West, the index fell 3.7 percent to 97.5 but remains 17.5 percent higher than December 2007.
“However, housing activity remains weak compared with potential demand, and the market is fragile given the economic backdrop,” says NAR President Charles McMillan. “We can’t take our eye off the need to stimulate housing, which can set the foundation for an economic recovery. Last week’s actions in the House to eliminate the repayment feature on the first-time home buyer tax credit, and to raise mortgage loan limits, are helpful. However, we need to take additional steps to meaningfully draw down inventory and stabilize home prices.”
McMillan says some enhancements that could bring more buyers into the market include expanding the $7,500 tax credit to all home buyers, extending it until the end of 2009, and making loan limit increases permanent. “We also need to direct funds in the Troubled Asset Relief Program (TARP) to add liquidity to the mortgage market, buy down mortgage interest rates and increase other forms of credit,” he says.
Yun says the outlook for housing and the economy is murky. “Although Congress and the Obama administration are taking steps to help the economy, the stimulus package must deal with the root cause of the economic downturn, and apply the right fix to turn it around. If housing is ignored, a significant downward overshooting of home prices would continue to drag the economy down independent of the scale of the stimulus,” Yun says.
© 2009 FLORIDA ASSOCIATION OF REALTORS®
Pending home sales increased as more buyers took advantage of improved affordability conditions, according to the National Association of Realtors® (NAR). Big gains in the South and Midwest offset modest declines in other regions.
The Pending Home Sales Index, a forward-looking indicator based on contracts signed in December, rose 6.3 percent to 87.7 from an upwardly revised reading of 82.5 in November, and is 2.1 percent higher than December 2007 when it was 85.9.
Lawrence Yun, NAR chief economist, says the index shows a modest rebound. “The monthly gain in pending home sales, spurred by buyers responding to lower home prices and mortgage interest rates, more than offset an index decline in the previous month,” he says. “The biggest gains were in areas with the biggest improvements in affordability.”
NAR’s Housing Affordability index rose 10.9 percent in December to 158.8, the highest on record. The HAI shows that the relationship between home prices, mortgage interest rates and family income is the most favorable since tracking began in 1970.“Significant uncertainty still clouds the housing market despite improved affordability conditions. For a sustainable housing market recovery and, hence, sustainable economic recovery, we need a significant housing stimulus and mortgage availability for qualified borrowers,” Yun added.
The PHSI in the Northeast slipped 1.7 percent to 62.1 in December and is 14.5 percent below a year ago. In the Midwest the index jumped 12.8 percent to 83.7 but remains 1.2 percent below December 2007.
The index in the South surged 13.0 percent to 96.8 in December and is 1.6 percent above a year ago. In the West, the index fell 3.7 percent to 97.5 but remains 17.5 percent higher than December 2007.
“However, housing activity remains weak compared with potential demand, and the market is fragile given the economic backdrop,” says NAR President Charles McMillan. “We can’t take our eye off the need to stimulate housing, which can set the foundation for an economic recovery. Last week’s actions in the House to eliminate the repayment feature on the first-time home buyer tax credit, and to raise mortgage loan limits, are helpful. However, we need to take additional steps to meaningfully draw down inventory and stabilize home prices.”
McMillan says some enhancements that could bring more buyers into the market include expanding the $7,500 tax credit to all home buyers, extending it until the end of 2009, and making loan limit increases permanent. “We also need to direct funds in the Troubled Asset Relief Program (TARP) to add liquidity to the mortgage market, buy down mortgage interest rates and increase other forms of credit,” he says.
Yun says the outlook for housing and the economy is murky. “Although Congress and the Obama administration are taking steps to help the economy, the stimulus package must deal with the root cause of the economic downturn, and apply the right fix to turn it around. If housing is ignored, a significant downward overshooting of home prices would continue to drag the economy down independent of the scale of the stimulus,” Yun says.
© 2009 FLORIDA ASSOCIATION OF REALTORS®
Friday, January 30, 2009
What Repeat Buyers Want From Their Agent!
What Repeat Buyers Want Most From Real Estate Professionals
Help you find the right house to purchase - 53%
Help with price negotiations - 13%
Tell you what comparable homes are selling for - 11%
Help determining how much buyer can afford - 11%
Help with paperwork - 8%
Help find and arrange financing - 2%
Help you find the right house to purchase - 53%
Help with price negotiations - 13%
Tell you what comparable homes are selling for - 11%
Help determining how much buyer can afford - 11%
Help with paperwork - 8%
Help find and arrange financing - 2%
How Buyers Find a Home!
Information Sources Used in Home Search
Real estate agent - 84%
Internet -84%
Yard sign - 59%
Open house - 48%
Home book/magazine - 31%
Builders - 24%
Television - 9%
Billboard - 7%
Relocation company - 5%
Real estate agent - 84%
Internet -84%
Yard sign - 59%
Open house - 48%
Home book/magazine - 31%
Builders - 24%
Television - 9%
Billboard - 7%
Relocation company - 5%
Thursday, January 29, 2009
Fannie Mae Tries Program to Speed Up ‘Short Sales’ in Orlando Area

By Jerry W. Jackson
RISMEDIA, January 29, 2009-(MCT)-Orlando is one of the leading metro areas in Florida for single-family-home resales, soaring past larger markets such as Miami, Fort Lauderdale and Jacksonville during the past year as local deals on distressed homes have mushroomed. Now the mortgage giant Fannie Mae is testing a small pilot program in Orlando to speed up some of those sales.
A “short sale” is a distress sale in which the lender agree to take less than the amount owed on the home’s mortgage, so it can avoid the costs of a foreclosure. The number of such deals has been rising in lock step with the surge in foreclosures the past year.
Orange, Seminole, Lake, Osceola and Volusia counties are among 11 counties in Central and Southwest Florida where about 300 homes have been preapproved by Fannie Mae for short sales. Orlando-area Realtors say they hope the program cuts the wait time on short-sale offers from months to weeks or even days-and prompts other lenders to move faster as well.
“Right now, short sales can take months and months until you get an answer back, and sometimes the answer is, ‘We’re not interested.’ This program will cut through that,” said Marty Hunt, an Orlando-area Realtor and president of the Mid-Florida Regional Multiple Listing Service.
The regional MLS, owned and operated by 13 Realtor associations in 10 counties, including the Orlando Regional Realtor Association, will flag the preapproved short sales so member agents can market them for quick sale. The pilot program, which began in late December, also is under way in Phoenix.
Hunt said the relatively small number of preapproved short sales in the Orlando area won’t do much to decrease the thousands of homes in some stage of foreclosure or already repossessed by banks. But if the pilot program works during the next few months, it would be extended and expanded, he said, and that would probably prompt other lenders to develop similar fast-track programs.
The pilot program crafted by Fannie Mae, formally known as the Federal National Mortgage Association, streamlines the process by getting all the research on a property and all the necessary clearances done in advance. In a typical short sale, an offer takes longer than a conventional sale to close because the offer must be cleared by multiple parties, and any negotiations on price can get lost in the blizzard of faxes and other paperwork.
Hunt said that if lenders decide upfront how much they are willing to accept, it would help move some of the record inventory now on the market, and that would help stabilize falling home values and boost consumer confidence.
“That’s critical to turning this around,” he said, noting that in some of the region’s newer subdivisions an estimated 50% to 60% of the homes on the market are foreclosures or short sales. The Fannie Mae pilot program will also include some listings in Polk, Hillsborough, southern Pasco, Manatee, Sarasota and Charlotte counties.
Copyright © 2009, The Orlando Sentinel, Fla.
Distributed by McClatchy-Tribune Information Services.
Wednesday, January 28, 2009
Habitat for Humanity Superbuild Update!
CONSTRUCTION IS GOING GREAT!
Day 1: The first day went very well. We met the Day 1 Build Schedule. Almost 200 volunteers turned out to raise the walls with our partner families! After the Wall Raising ceremony, the volunteers reported to their assigned house site for safety speeches to start the work day. Everyone worked hard and had a lot of fun!
Day 2: It was a beautiful day in the Habitat neighborhood as volunteers joined together to put sheathing on the roof of each home, among other tasks. Members of the Unitarian Universalist Church brought delicious chili to help feed the volunteers. Mid-afternoon milk and cookies helped our wonderful volunteers meet the Build Schedule for Day 2!
Day 3: The roosters were crowing this morning (both the real kind and the iPod species) to get the volunteers started on their day of building for SuperBuild 2009. The sun was shining brightly as workers put felt paper on the roof to prepare for shingling while other volunteers installed siding. Electricians and plumbers worked inside to install wiring and plumbing fixtures. What a busy and productive day! We are still on schedule!! Go volunteers, Crew Leaders and House Leaders!! You rock!
Day 4: The weather was wonderful for building today! Our super volunteers worked hard installing siding, shingles and insulation today. We are still on track!! Pod species) to get the volunteers started on their day of building for SuperBuild 2009. The sun was shining brightly as workers put felt paper on the roof to prepare for shingling.
Day 5: Volunteers did a great job installing siding and shingles. It was exciting when Mayor Pam Iorior came out to the site to draw the name of the winner of the Super Bowl tickets from the "Square Up for $59" campaign for the Champions House. Later in the day, volunteers and drywall installers took a break when Warrick Dunn made a presentation to another Habitat homeowner from the Warrick Dunn Foundation. Our wonderful volunteers could not wait to get back to work. Thank you for your dedication!!
Day 1: The first day went very well. We met the Day 1 Build Schedule. Almost 200 volunteers turned out to raise the walls with our partner families! After the Wall Raising ceremony, the volunteers reported to their assigned house site for safety speeches to start the work day. Everyone worked hard and had a lot of fun!
Day 2: It was a beautiful day in the Habitat neighborhood as volunteers joined together to put sheathing on the roof of each home, among other tasks. Members of the Unitarian Universalist Church brought delicious chili to help feed the volunteers. Mid-afternoon milk and cookies helped our wonderful volunteers meet the Build Schedule for Day 2!
Day 3: The roosters were crowing this morning (both the real kind and the iPod species) to get the volunteers started on their day of building for SuperBuild 2009. The sun was shining brightly as workers put felt paper on the roof to prepare for shingling while other volunteers installed siding. Electricians and plumbers worked inside to install wiring and plumbing fixtures. What a busy and productive day! We are still on schedule!! Go volunteers, Crew Leaders and House Leaders!! You rock!
Day 4: The weather was wonderful for building today! Our super volunteers worked hard installing siding, shingles and insulation today. We are still on track!! Pod species) to get the volunteers started on their day of building for SuperBuild 2009. The sun was shining brightly as workers put felt paper on the roof to prepare for shingling.
Day 5: Volunteers did a great job installing siding and shingles. It was exciting when Mayor Pam Iorior came out to the site to draw the name of the winner of the Super Bowl tickets from the "Square Up for $59" campaign for the Champions House. Later in the day, volunteers and drywall installers took a break when Warrick Dunn made a presentation to another Habitat homeowner from the Warrick Dunn Foundation. Our wonderful volunteers could not wait to get back to work. Thank you for your dedication!!
Florida Consumer Confidence Inches Upward!
Floridians' consumer confidence is inching back up, gaining one point to stand at 68, despite the weak economy, according to the latest survey from UF's economists. The biggest change may be in the component measuring perceptions of personal finances now compared with a year ago, which broke a four-month downward trend to rise five points.
Tuesday, January 27, 2009
State Farm Planning To Pull Out as Florida Property Insurance Provider
TALLAHASSEE, Fla. – Jan. 27, 2009 – State Farm announced today that it’s pulling out of the property insurance market throughout Florida.State Farm Florida – the state’s largest private homeowners insurer – estimates that the move will impact up to a million customers. The company plans to continue its other insurance divisions, including auto, which has about 2.8 million customers.State Farm blames the state for its move. On Jan. 12, Florida regulators denied a State Farm request for a 47 percent average rate increase.“Although this is disappointing news for Floridians who have been loyal customers of State Farm, we are not surprised by State Farm’s decision to stop offering all property insurance in Florida,” says Florida Insurance Commissioner Kevin McCarty. “We have been hearing for months of possible plans to make such a move in Florida, including a document submitted … as recently as Dec. 5.” McCarty says the state will carefully review State Farm’s plans and “explore all legal options as well.”The Florida Legislature could also become involved. “It is important to note that we have been working with state Sen. Mike Fasano, (R-New Port Richey) to develop legislation that will significantly limit the number of non-renewals a company can issue in a year,” McCarty says.Current State Farm policyholders will not see any changes in the near future. The Office of Insurance Regulation has 90 days to approve State Farm’s plan. If approved, State Farm must then provide 180 days notice to customers before any policies can be non-renewed.
© 2009 FLORIDA ASSOCIATION OF REALTORS®
© 2009 FLORIDA ASSOCIATION OF REALTORS®
Monday, January 26, 2009
More Good Housing News!
DECEMBER HOME SALES
Florida's existing home sales rose 27 percent in December, making it the fourth consecutive month that sales activity demonstrated gains in the year-to-year comparison, according to FAR. Statewide sales of existing condos increased 12 percent last month; and December sales of both existing homes and condos were higher than November's statewide figures. Meanwhile, NAR reports that existing-home sales - all housing types - rose 6.5 percent in December compared to November's pace.
Florida's existing home sales rose 27 percent in December, making it the fourth consecutive month that sales activity demonstrated gains in the year-to-year comparison, according to FAR. Statewide sales of existing condos increased 12 percent last month; and December sales of both existing homes and condos were higher than November's statewide figures. Meanwhile, NAR reports that existing-home sales - all housing types - rose 6.5 percent in December compared to November's pace.
RIVERVIEW, NEW LISTING! FOR RENT! 10435 Hunters Haven


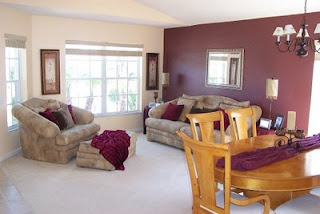


Be the first to step inside this impeccable home set on a large, fenced lot with a pond view! It offers formal living & dining rooms as well as a casual kitchen and family room inside 1,856 square feet. The open kitchen features upgraded cabinets & appliances, a closet pantry, breakfast bar & a dining area. This popular floor plan; the Dakota, by Pulte offers a split bedroom design with the volume ceilings & art niches you expect with a newer home. The master, overlooking the backyard, includes a deep walk-in closet & a private bath with his/her sinks, garden tub & separate shower. The yard offers plenty of room for outdoor play, 3 gates for easy entry, & a pond view with no backyard neighbor beyond the quality wooden fence! What’s more, all of this can be enjoyed from the generous, 18-by-24-foot screened lanai. Other extras include lovely landscaping & new, 18” in tile floors in the kitchen & all wet areas & walk ways. South Pointe boasts 2 community pools, a community park, & easy access to U.S. 301 or Interstate 75 for downtown commuters. This one’s an easy pick! $1300/month Available June 1, 2009
Friday, January 23, 2009
Riverglen Open House! Sunday 1/25/09 2-4PM


Come see this nearly 2400sf home being held open Sunday, January 25, 2009 from 2PM-4PM! This stunning 5BR, 3BA home. Upgrades include 16 inch tile set on the diagonal, remodeled bathrooms, designer lighting and fixtures, stainless-steel appliances and a new high-efficiency A/C unit. Property is located at 12017 Running Fox in Riverview. NOT A SHORT SALE! Aggressively priced at $104sf, same as the bank owned across the street. A 200sf, smaller home next door sold at $108sf last month. Great Schools! Low HOA fees. Easy commute to Tampa, MacDill and surrounding areas.
Few Borrowers Can Revise Mortgage Loans
By Monica Hatcher
RISMEDIA, January 23, 2009-(MCT)-Since defaulting on her mortgage more than a year ago, Marisela Gonzalez has attended foreclosure prevention seminars, spent hours on the phone with her lender, paid a consultant, availed herself of bankruptcy protection-everything in her power to hang onto her home.
“I thought to pack and just get out,” recalled the special-education teacher. “Then, I said, ‘No … this is my place. I’ve been here 15 years and I am not going to give it back to a bank just like that.’”
Yet Gonzalez is giving her Kendall, Fla., townhouse back to the bank, in this case the federal government, which took over lender IndyMac. Even with an offer to lower her interest rate, Gonzalez could not afford the payments and owes about $100,000 more than the house is worth.
Gonzalez’s attempts to stay in her home illustrate why regulators are having trouble stemming the flood of foreclosures at the heart of the nation’s economic crisis. And why some say it is imperative for the economy that a major chunk of the remaining $700 billion bailout bonanza go to helping homeowners drowning in debt.
Regulators, lawmakers and economists alike believe helping borrowers get into loans with more favorable terms-smaller loans, lower interest rates-is crucial to ending the recession. But despite the creation of a number of programs, only a small percentage of struggling homeowners have received help.
Lenders, watching out for their bottom lines, will go along only as long as helping the borrower will cost them less than foreclosing and reselling the home. Plus, they are skittish about staying on the hook with borrowers who are highly likely to default again.
Borrowers, for their part, often can’t afford the reduced payments. When they can, they question the sense of paying on a home that, as is the case in many places, is still falling in value. Investors, who represent a big slice of delinquent homeowners, do not qualify for a mortgage lifeline at all.
No one questions that the need is dire. Regulators from Federal Deposit Insurance Corp. Chairman Sheila Bair to Federal Reserve Chairman Ben Bernanke and the U.S. Treasury’s Neel Kashkari have repeatedly told Congress that more must be done to prevent foreclosures and stabilize falling home prices, saying both are required to lift the economy out of recession.
In November, the FDIC estimated that another 3.8 million mortgages would be 60 days to 90 days past due by the end of 2009.
Yet even the government’s own effort to modify loans, which is being held out as a national model for other lenders, has its flaws, housing advocates and other market observers said.
Of the 45,000 borrowers eligible for a workout under an FDIC program, 8,500 loans have been restructured. “Thousands more,” though, are in the pipeline, the FDIC said. The agency would not say how many borrowers could not be helped. And Hope for Homeowners, passed by Congress in July, was expected to help 400,000 borrowers avoid foreclosure with Federal Housing Administration guarantees of up to $300 billion in refinanced loans.
So far, only 350 loans nationwide have been refinanced, according to the U.S. Department of Housing and Urban Development.
The reason: Lenders have to agree to write the value of the loan down to 90% of the home’s current market value. Homeowners have to share half of any future equity with the federal government. Neither are eager to do that.
The numbers disappoint Guy Cecala, publisher of Inside Mortgage Finance, who asserts that across-the-board, automatic modifications are needed to contain the wreckage of the last six years. That might have been possible had bailout funds been used to buy mortgage-backed securities, putting control of the loans in the government’s hands rather than Wall Street investors, he said.
“If this is the best model we’ve got, we’re still in trouble,” Cecala said. “It is probably the most aggressive we’ve seen out there and you are still not getting a lot of success.”
It’s not clear what system will be used to implement a sweeping foreclosure-prevention program pledged by President Barack Obama during negotiations with Congress over the release last week of $350 billion in bailout funds.
Loan modifications are different from repayment plans, which help borrowers catch up on missed payments by doing things like folding past-due amounts into the mortgage balance or boosting monthly payments by a small amount to pay arrears a bit at a time. Generally, they’re meant to see borrowers through a temporary rough patch.
Modifications take aim at the mortgage’s structure. Plans can include converting adjustable interest rates to fixed, lowering rates and, in rare cases, forgiving some of the principal. Banks often will extend the life of the loan to reduce monthly payments as well.
Under intense public pressure, lenders have amped up loan modifications.
Hope Now, an alliance of nonprofits, lenders and the federal government, said more than 850,000 loans were modified through November.
The FDIC says only 4% of seriously delinquent loans each month are being modified. And data from the Office of the Comptroller of the Currency suggests the modifications may ultimately not be much help. The OCC found recently that 37% of mortgages modified in the first quarter of 2008 were 60 days past due within six months.
“Maybe the loan modification did not cut far enough; it may be that the loan was so poorly underwritten that nothing could help the borrower,” said Bryan Hubbard, an OCC spokesman. “It may be that borrower had more credit available and used it for other means and ran up debt elsewhere and the economy has taken a turn for the worse.”
Avi Shenkar, president of GMA Modification in North Miami Beach, Fla., said modifications still weren’t lowering payments enough for borrowers who took out teaser rate loans and owe far more then they could afford.
He also questions how willing banks are to work with homeowners, since eight out of 10 seeking help from GMA already have been denied a modification from the bank.
Jackie Duran, director of foreclosure prevention at the nonprofit Neighborhood Housing Services of South Florida, said many of their clients also got nowhere dealing with the bank.
“It’s obvious to us that lenders are not trying to help the homeowner but minimize how much they lose. They have a very thin margin for loan modification,” Shenkar said.
Gonzalez’s lender, IndyMac, looks at two things: whether modifying a borrower’s loan costs less than its estimated cost to foreclose, and whether payments can be reduced at least 10% and still account for no more than 38% of a borrower’s monthly income.
“We contractually have to act in the interest of whoever owns the loan,” said Evan Wagner, an IndyMac spokesman. Wagner said the bank has mailed offers to most of those eligible for a modification, a feat, considering the program has been in effect for only around six months.
Even when payments can be reduced, homeowners have to be convinced that sticking with a loan that is higher than the home’s market value-known as being underwater-is in their best interest.
That’s the main reason Gonzalez has decided to walk away. Gonzalez refinanced in 2006 into an option-ARM with a balance that grew over time, rolling in other debt like credit cards.
“I refinance for $245,000. I owe now $286,000-$41,000 was of the negative amortization in a year,” Gonzalez said. Her home’s worth: $175,000.
Wagner said Gonzalez was offered a deal almost a year ago that kept her payments essentially the same and reduced her interest rate to a fixed 8.4%. She insists she was told differently.
There’s little IndyMac can do for her now, Wagner said, since Gonzalez’s debts were discharged in bankruptcy court. She’ll have to leave her home soon.
“Where is the federal help for homeowners? Homeowners are losing in this deal and the banks are … not losing anything,” Gonzalez said.
But loan modifications are not about making homes better investments for borrowers, Wagner said. In fact, most homeowners will be worse off after their arrears, interest and fees are rolled into the balance after a modification, he said.“Our program is about affordability,” Wagner said. “… not about mitigating bad investment decisions. We’re not getting into that.”
IndyMac’s plan, he said, allows the bank to “help those that we can without encouraging the 90 percent of people who are making payments not to default themselves,” he said.
Cecala said many homeowners figure that if a modification’s goal is solely to have their monthly payments lowered, they’d be better off renting, thinking there was little hope of ever having equity.
“What they need to do is build an incentive to keep somebody in the home,” Cecala said.
As for Gonzalez, she’s fought, agonized and cried, but has finally come to terms with the idea of leaving her townhouse.
“At this point, I don’t really care. I’m tired of this BS,” Gonzalez said.
© 2009, The Miami Herald.Distributed by McClatchy-Tribune Information Services.
RISMEDIA, January 23, 2009-(MCT)-Since defaulting on her mortgage more than a year ago, Marisela Gonzalez has attended foreclosure prevention seminars, spent hours on the phone with her lender, paid a consultant, availed herself of bankruptcy protection-everything in her power to hang onto her home.
“I thought to pack and just get out,” recalled the special-education teacher. “Then, I said, ‘No … this is my place. I’ve been here 15 years and I am not going to give it back to a bank just like that.’”
Yet Gonzalez is giving her Kendall, Fla., townhouse back to the bank, in this case the federal government, which took over lender IndyMac. Even with an offer to lower her interest rate, Gonzalez could not afford the payments and owes about $100,000 more than the house is worth.
Gonzalez’s attempts to stay in her home illustrate why regulators are having trouble stemming the flood of foreclosures at the heart of the nation’s economic crisis. And why some say it is imperative for the economy that a major chunk of the remaining $700 billion bailout bonanza go to helping homeowners drowning in debt.
Regulators, lawmakers and economists alike believe helping borrowers get into loans with more favorable terms-smaller loans, lower interest rates-is crucial to ending the recession. But despite the creation of a number of programs, only a small percentage of struggling homeowners have received help.
Lenders, watching out for their bottom lines, will go along only as long as helping the borrower will cost them less than foreclosing and reselling the home. Plus, they are skittish about staying on the hook with borrowers who are highly likely to default again.
Borrowers, for their part, often can’t afford the reduced payments. When they can, they question the sense of paying on a home that, as is the case in many places, is still falling in value. Investors, who represent a big slice of delinquent homeowners, do not qualify for a mortgage lifeline at all.
No one questions that the need is dire. Regulators from Federal Deposit Insurance Corp. Chairman Sheila Bair to Federal Reserve Chairman Ben Bernanke and the U.S. Treasury’s Neel Kashkari have repeatedly told Congress that more must be done to prevent foreclosures and stabilize falling home prices, saying both are required to lift the economy out of recession.
In November, the FDIC estimated that another 3.8 million mortgages would be 60 days to 90 days past due by the end of 2009.
Yet even the government’s own effort to modify loans, which is being held out as a national model for other lenders, has its flaws, housing advocates and other market observers said.
Of the 45,000 borrowers eligible for a workout under an FDIC program, 8,500 loans have been restructured. “Thousands more,” though, are in the pipeline, the FDIC said. The agency would not say how many borrowers could not be helped. And Hope for Homeowners, passed by Congress in July, was expected to help 400,000 borrowers avoid foreclosure with Federal Housing Administration guarantees of up to $300 billion in refinanced loans.
So far, only 350 loans nationwide have been refinanced, according to the U.S. Department of Housing and Urban Development.
The reason: Lenders have to agree to write the value of the loan down to 90% of the home’s current market value. Homeowners have to share half of any future equity with the federal government. Neither are eager to do that.
The numbers disappoint Guy Cecala, publisher of Inside Mortgage Finance, who asserts that across-the-board, automatic modifications are needed to contain the wreckage of the last six years. That might have been possible had bailout funds been used to buy mortgage-backed securities, putting control of the loans in the government’s hands rather than Wall Street investors, he said.
“If this is the best model we’ve got, we’re still in trouble,” Cecala said. “It is probably the most aggressive we’ve seen out there and you are still not getting a lot of success.”
It’s not clear what system will be used to implement a sweeping foreclosure-prevention program pledged by President Barack Obama during negotiations with Congress over the release last week of $350 billion in bailout funds.
Loan modifications are different from repayment plans, which help borrowers catch up on missed payments by doing things like folding past-due amounts into the mortgage balance or boosting monthly payments by a small amount to pay arrears a bit at a time. Generally, they’re meant to see borrowers through a temporary rough patch.
Modifications take aim at the mortgage’s structure. Plans can include converting adjustable interest rates to fixed, lowering rates and, in rare cases, forgiving some of the principal. Banks often will extend the life of the loan to reduce monthly payments as well.
Under intense public pressure, lenders have amped up loan modifications.
Hope Now, an alliance of nonprofits, lenders and the federal government, said more than 850,000 loans were modified through November.
The FDIC says only 4% of seriously delinquent loans each month are being modified. And data from the Office of the Comptroller of the Currency suggests the modifications may ultimately not be much help. The OCC found recently that 37% of mortgages modified in the first quarter of 2008 were 60 days past due within six months.
“Maybe the loan modification did not cut far enough; it may be that the loan was so poorly underwritten that nothing could help the borrower,” said Bryan Hubbard, an OCC spokesman. “It may be that borrower had more credit available and used it for other means and ran up debt elsewhere and the economy has taken a turn for the worse.”
Avi Shenkar, president of GMA Modification in North Miami Beach, Fla., said modifications still weren’t lowering payments enough for borrowers who took out teaser rate loans and owe far more then they could afford.
He also questions how willing banks are to work with homeowners, since eight out of 10 seeking help from GMA already have been denied a modification from the bank.
Jackie Duran, director of foreclosure prevention at the nonprofit Neighborhood Housing Services of South Florida, said many of their clients also got nowhere dealing with the bank.
“It’s obvious to us that lenders are not trying to help the homeowner but minimize how much they lose. They have a very thin margin for loan modification,” Shenkar said.
Gonzalez’s lender, IndyMac, looks at two things: whether modifying a borrower’s loan costs less than its estimated cost to foreclose, and whether payments can be reduced at least 10% and still account for no more than 38% of a borrower’s monthly income.
“We contractually have to act in the interest of whoever owns the loan,” said Evan Wagner, an IndyMac spokesman. Wagner said the bank has mailed offers to most of those eligible for a modification, a feat, considering the program has been in effect for only around six months.
Even when payments can be reduced, homeowners have to be convinced that sticking with a loan that is higher than the home’s market value-known as being underwater-is in their best interest.
That’s the main reason Gonzalez has decided to walk away. Gonzalez refinanced in 2006 into an option-ARM with a balance that grew over time, rolling in other debt like credit cards.
“I refinance for $245,000. I owe now $286,000-$41,000 was of the negative amortization in a year,” Gonzalez said. Her home’s worth: $175,000.
Wagner said Gonzalez was offered a deal almost a year ago that kept her payments essentially the same and reduced her interest rate to a fixed 8.4%. She insists she was told differently.
There’s little IndyMac can do for her now, Wagner said, since Gonzalez’s debts were discharged in bankruptcy court. She’ll have to leave her home soon.
“Where is the federal help for homeowners? Homeowners are losing in this deal and the banks are … not losing anything,” Gonzalez said.
But loan modifications are not about making homes better investments for borrowers, Wagner said. In fact, most homeowners will be worse off after their arrears, interest and fees are rolled into the balance after a modification, he said.“Our program is about affordability,” Wagner said. “… not about mitigating bad investment decisions. We’re not getting into that.”
IndyMac’s plan, he said, allows the bank to “help those that we can without encouraging the 90 percent of people who are making payments not to default themselves,” he said.
Cecala said many homeowners figure that if a modification’s goal is solely to have their monthly payments lowered, they’d be better off renting, thinking there was little hope of ever having equity.
“What they need to do is build an incentive to keep somebody in the home,” Cecala said.
As for Gonzalez, she’s fought, agonized and cried, but has finally come to terms with the idea of leaving her townhouse.
“At this point, I don’t really care. I’m tired of this BS,” Gonzalez said.
© 2009, The Miami Herald.Distributed by McClatchy-Tribune Information Services.
Thursday, January 22, 2009
HOPE For Homeowners Program
WHAT IS HOPE FOR HOMEOWNERS?
When the subprime mortgage crisis reached its peak in the fall of 2008, the federal government took steps to help stabilize the American housing market. The Emergency Economic Stabilization Act of 2008 was signed into law on October 3, 2008. Part of that new law includes a requirement to help qualified homeowners avoid foreclosure through federal loan guarantees and credit enhancements.
When you are approved for refinancing under the HOPE for Homeowners program, you’re required to participate in equity sharing with the FHA. The HOPE for Homeowners act is designed to prevent qualified home owners from defaulting on their loans, and avert foreclosure. This is done through refinancing into affordable, fixed-rate mortgages. If you are in danger of defaulting on your home loan, it’s very important to contact your lender immediately and request an evaluation of your situation. If you are able to qualify, your loan officer can help you begin the paperwork to prevent foreclosure. If you are already in discussions with the bank, your loan officer may suggest HOPE for Homeowners as a way to proceed.
AM I ELIGIBLE?
Homeowners may be eligible for HOPE for Homeowners program if they meet the following criteria as specified in the HOPE for Homeowners act 2008:
The original mortgage is dated on or before January 1, 2008
The homeowner did not default on the original loan intentionally
The homeowner is not invested in multiple home loans
All information on the original mortgage is true (including income sources and job details)
The homeowner has not been convicted of fraud HOPE for Homeowners is not a simple refinancing program. While it does allow qualified borrowers who are stuck in variable-rate mortgages to refinance into affordable, fixed-rate mortgages, there is a trade-off known as equity sharing.
WHAT IS EQUITY SHARING?
Those who apply and are accepted for the HOPE program must agree to an equity sharing program. Equity is the difference between the amount of your original loan and the actual value of the home; if you sell or refinance your home after entering the HOPE program, under the terms of HOPE you are required to share any equity with the FHA. How much the government receives depends on how long you wait to sell or refinance. If you sell in the first year of your participation in HOPE, the government receives 100% of the equity. There is a sliding scale after the first year;
Year two—homeowners can keep 10% of the equity, FHA gets 90%
Year three—homeowners keep 20%, FHA gets 80%
Year four—homeowners keep 30%, FHA gets 70%
Year five—homeowners keep 40%, FHA gets 60%
After year five, homeowners split the equity from sale or refinancing 50/50 with the Federal Housing Administration. If there is no equity or negative equity at the time of sale or refinancing, the FHA receives nothing.
WHAT ARE THE BENEFITS OF HOPE?
The benefits of participating in HOPE for Homeowners include;
Keeping your home
Getting a 30-year fixed-rate mortgage (extendable to 40 years in some cases)
Lower monthly mortgage payments which do not change The 30-year loan is extendable in some situations. Extending the terms to 40 years is helpful in cases where the homeowner has a large amount of debt; the 40-year term reduces mortgage payments further. There are requirements and restrictions on these extended loans. Check with your lender to see if you qualify for the 40-year loan terms under the HOPE program. The HOPE for Homeowners program runs until September 20, 2011.
When the subprime mortgage crisis reached its peak in the fall of 2008, the federal government took steps to help stabilize the American housing market. The Emergency Economic Stabilization Act of 2008 was signed into law on October 3, 2008. Part of that new law includes a requirement to help qualified homeowners avoid foreclosure through federal loan guarantees and credit enhancements.
When you are approved for refinancing under the HOPE for Homeowners program, you’re required to participate in equity sharing with the FHA. The HOPE for Homeowners act is designed to prevent qualified home owners from defaulting on their loans, and avert foreclosure. This is done through refinancing into affordable, fixed-rate mortgages. If you are in danger of defaulting on your home loan, it’s very important to contact your lender immediately and request an evaluation of your situation. If you are able to qualify, your loan officer can help you begin the paperwork to prevent foreclosure. If you are already in discussions with the bank, your loan officer may suggest HOPE for Homeowners as a way to proceed.
AM I ELIGIBLE?
Homeowners may be eligible for HOPE for Homeowners program if they meet the following criteria as specified in the HOPE for Homeowners act 2008:
The original mortgage is dated on or before January 1, 2008
The homeowner did not default on the original loan intentionally
The homeowner is not invested in multiple home loans
All information on the original mortgage is true (including income sources and job details)
The homeowner has not been convicted of fraud HOPE for Homeowners is not a simple refinancing program. While it does allow qualified borrowers who are stuck in variable-rate mortgages to refinance into affordable, fixed-rate mortgages, there is a trade-off known as equity sharing.
WHAT IS EQUITY SHARING?
Those who apply and are accepted for the HOPE program must agree to an equity sharing program. Equity is the difference between the amount of your original loan and the actual value of the home; if you sell or refinance your home after entering the HOPE program, under the terms of HOPE you are required to share any equity with the FHA. How much the government receives depends on how long you wait to sell or refinance. If you sell in the first year of your participation in HOPE, the government receives 100% of the equity. There is a sliding scale after the first year;
Year two—homeowners can keep 10% of the equity, FHA gets 90%
Year three—homeowners keep 20%, FHA gets 80%
Year four—homeowners keep 30%, FHA gets 70%
Year five—homeowners keep 40%, FHA gets 60%
After year five, homeowners split the equity from sale or refinancing 50/50 with the Federal Housing Administration. If there is no equity or negative equity at the time of sale or refinancing, the FHA receives nothing.
WHAT ARE THE BENEFITS OF HOPE?
The benefits of participating in HOPE for Homeowners include;
Keeping your home
Getting a 30-year fixed-rate mortgage (extendable to 40 years in some cases)
Lower monthly mortgage payments which do not change The 30-year loan is extendable in some situations. Extending the terms to 40 years is helpful in cases where the homeowner has a large amount of debt; the 40-year term reduces mortgage payments further. There are requirements and restrictions on these extended loans. Check with your lender to see if you qualify for the 40-year loan terms under the HOPE program. The HOPE for Homeowners program runs until September 20, 2011.
Non-Vacant Vacant Homes
Some real estate pros encourage sellers of vacant properties to move house sitters in to ensure security and keep the home ready for showings. In Spokane, Wash., Diana and Kevin Uphus of Select Real Estate launched Diana's Home Sitting Services in 2000 to locate house sitters for clients. House sitters pay $400 per month to live in the home, and they also cover the utility bills. When choosing a house sitter, the Uphuses perform background checks on candidates - whom must be able to leave at a moment's notice for showings, carry $100,000 in personal liability coverage, perform simple maintenance and keep the home clean. They also ensure the sitter's furniture is in good shape and complements the home's decor.
Source:Realtor (01/09) Vol. 42, No. 1, P. 18; Tracey, Melissa Dittmann© Copyright 2009 INFORMATION, INC. Bethesda, MD (301) 215-4688
Source:Realtor (01/09) Vol. 42, No. 1, P. 18; Tracey, Melissa Dittmann© Copyright 2009 INFORMATION, INC. Bethesda, MD (301) 215-4688
Citizen's Insurance Increase?
JACKSONVILLE, Fla. (AP) – Jan. 23, 2009 – A task force is recommending that Citizens Property Insurance be allowed to end a three-year rate freeze and start aggressively hiking homeowner rates. The task force voted earlier this month to recommend that the Legislature caps Citizens’ annual rate increase to 10 percent on average statewide. It was meeting again Thursday in Jacksonville to finalize its report. It also suggests an annual cap of 15 percent for any given territory and 20 percent for any single policy. Task force members are urging the state for Citizens to begin raising rates in January 2010. Citizens is the state’s largest insurer with 1.1 million policies and $412 billion in exposure. The task force must submit a report to the Legislature by Jan. 31.
Copyright 2009 The Associated Press.
Copyright 2009 The Associated Press.
Tuesday, January 20, 2009
Foreclosed Homes Can Be Good Deals, Bargains for Buyers!

By LaTina Emerson
RISMEDIA, January 20, 2009-(MCT)-Buying a foreclosure property was Amanda Rasch’s only hope of owning her own home. After fleeing New Orleans to escape Hurricane Katrina in 2005, Rasch, her husband and two children lived with her parents in a small Augusta house purchased with her parents’ Federal Emergency Management Agency evacuee housing vouchers.
Money was tight, but they were able to start looking for a home in late 2007.
In April, they bought a four-bedroom house in Martinez for $111,000. It had been valued at $135,000. Real estate agents say similar deals are available on foreclosure property throughout the Augusta area.
The Rasch family bought their home through Century 21 agent Jeff Keller III. Mr. Keller said homes that are available because a bank foreclosed on a previous owner sell for a “wholesale price.”
Buyers can find foreclosure properties up to 40% off their market value, he explained.
He tells clients who prefer not to buy foreclosures that they’re “probably cutting out easily 50% of the marketplace in Richmond County, as opposed to North Augusta, Columbia, McDuffie or Jefferson.”
The process for buying a foreclosure property through a real estate agent is the same as a normal purchase. Buyers must verify their income, have good credit and be able to show they can make their mortgage payments, said Bob Hale, the owner of Bob Hale Realty on Deans Bridge Road.
Short Sales or pre-foreclosures, allow potential buyers to bargain with the mortgage company.
“Mortgage companies do short sales when they don’t want to keep them on their books,” said Augusta broker Ira Tindall, the owner of RE/MAX Masters on Washington Road.
Usually, the mortgage holder is willing to take a lower price for the home. For instance, it might sell a $200,000 home for $180,000 simply to get rid of it, Mr. Tindall said.
Short sales can be initiated from foreclosure notices printed in the newspaper, though that is rare, he said.
Also, if homeowners think they might lose their home, they could contact their mortgage company, which would then contact a realty agent about selling the property as a short sale.
If a buyer is interested, the mortgage company can begin the sale of the home.
Because the company does not yet have the title, though, the current homeowner must become involved in the process, Tindall said. He said that some homeowners might refuse to participate because they are embarrassed about losing their home but that the process is a win-win situation for everyone.
“The owner doesn’t have a foreclosed piece of property on their record, the mortgage company gets what they want and the buyer usually gets a better buy,” he explained.
Buyers of homes at auctions on the courthouse steps purchase a house as-is. They might have seen the outside of the house, but they won’t have any idea what’s on the inside, Hale said.
“All foreclosure properties are not a good deal. Everything that looks rosy isn’t a rose,” he said.
Home buyers should rely on professionals, such as real estate agents and home inspectors, to make informed purchases, said Keri Mason Roth, a partner at Atlanta-based law firm Morris Hardwick Schneider. These professionals can provide information on the neighborhood, tax history, and details about the property, such as lot size, footage or homeowners association dues.
Foreclosure notices must be printed in the newspaper for four weeks before they are taken to the courthouse steps, Tindall said.
These proceedings take place on the first Tuesday of the month in Richmond and Columbia counties, he added.
In Aiken County, they are held the first Monday of each month inside the courthouse, rather than on the courthouse steps. If that day is a holiday, the auction is held on Tuesday, according to the county’s website.
Anyone can bid on foreclosure property, but buyers must pay in full with cash or a certified check after the sale.
“It usually takes you two or three weeks to get the title. If people are still in the house, you will have to go through eviction procedures,” he explained.
There might also be back taxes due or liens on the property, Roth said.
Also, it’s not as easy to find a bargain at the courthouse steps, Mr. Hale said. Lenders are present, and they’re seeking the amount owed on the property. Buyers can find better deals, as well as security, through a real estate agent, he added.
Property auctions are another way to find foreclosure properties, though it will likely take more time to close the transaction.
It’s worth it, however, because the auctions provide huge savings without financial surprises, such as back taxes, Roth said.
Buyers should still visit the property in advance to know what they’re bidding on, she said.
Banks or Mortgage companies might decide not to auction homes in their possession, which are referred to as real estate owned property, or REOs.
Instead, they ask real estate companies to list the properties in the multiple-listing service, as though they were normal vacant homes.
Houses that don’t sell on the courthouse steps are also added to this database, making the property available to all licensed real estate agents in the area, Tindall said.
In addition, deals are available with financing, Rasch said. Through an offer with the U.S. Department of Housing of Urban Development, her family was able to put only $100 down and use the down payment money to reduce the interest rate. The deal was available because the home was a foreclosure property, she said.
Rasch said they found their home at a good time; she has a toddler.
“Without this, we’d still be cramped in with my parents,” she said.
Copyright © 2009, The Augusta Chronicle, Ga. Distributed by McClatchy-Tribune Information Services.
RISMEDIA, January 20, 2009-(MCT)-Buying a foreclosure property was Amanda Rasch’s only hope of owning her own home. After fleeing New Orleans to escape Hurricane Katrina in 2005, Rasch, her husband and two children lived with her parents in a small Augusta house purchased with her parents’ Federal Emergency Management Agency evacuee housing vouchers.
Money was tight, but they were able to start looking for a home in late 2007.
In April, they bought a four-bedroom house in Martinez for $111,000. It had been valued at $135,000. Real estate agents say similar deals are available on foreclosure property throughout the Augusta area.
The Rasch family bought their home through Century 21 agent Jeff Keller III. Mr. Keller said homes that are available because a bank foreclosed on a previous owner sell for a “wholesale price.”
Buyers can find foreclosure properties up to 40% off their market value, he explained.
He tells clients who prefer not to buy foreclosures that they’re “probably cutting out easily 50% of the marketplace in Richmond County, as opposed to North Augusta, Columbia, McDuffie or Jefferson.”
The process for buying a foreclosure property through a real estate agent is the same as a normal purchase. Buyers must verify their income, have good credit and be able to show they can make their mortgage payments, said Bob Hale, the owner of Bob Hale Realty on Deans Bridge Road.
Short Sales or pre-foreclosures, allow potential buyers to bargain with the mortgage company.
“Mortgage companies do short sales when they don’t want to keep them on their books,” said Augusta broker Ira Tindall, the owner of RE/MAX Masters on Washington Road.
Usually, the mortgage holder is willing to take a lower price for the home. For instance, it might sell a $200,000 home for $180,000 simply to get rid of it, Mr. Tindall said.
Short sales can be initiated from foreclosure notices printed in the newspaper, though that is rare, he said.
Also, if homeowners think they might lose their home, they could contact their mortgage company, which would then contact a realty agent about selling the property as a short sale.
If a buyer is interested, the mortgage company can begin the sale of the home.
Because the company does not yet have the title, though, the current homeowner must become involved in the process, Tindall said. He said that some homeowners might refuse to participate because they are embarrassed about losing their home but that the process is a win-win situation for everyone.
“The owner doesn’t have a foreclosed piece of property on their record, the mortgage company gets what they want and the buyer usually gets a better buy,” he explained.
Buyers of homes at auctions on the courthouse steps purchase a house as-is. They might have seen the outside of the house, but they won’t have any idea what’s on the inside, Hale said.
“All foreclosure properties are not a good deal. Everything that looks rosy isn’t a rose,” he said.
Home buyers should rely on professionals, such as real estate agents and home inspectors, to make informed purchases, said Keri Mason Roth, a partner at Atlanta-based law firm Morris Hardwick Schneider. These professionals can provide information on the neighborhood, tax history, and details about the property, such as lot size, footage or homeowners association dues.
Foreclosure notices must be printed in the newspaper for four weeks before they are taken to the courthouse steps, Tindall said.
These proceedings take place on the first Tuesday of the month in Richmond and Columbia counties, he added.
In Aiken County, they are held the first Monday of each month inside the courthouse, rather than on the courthouse steps. If that day is a holiday, the auction is held on Tuesday, according to the county’s website.
Anyone can bid on foreclosure property, but buyers must pay in full with cash or a certified check after the sale.
“It usually takes you two or three weeks to get the title. If people are still in the house, you will have to go through eviction procedures,” he explained.
There might also be back taxes due or liens on the property, Roth said.
Also, it’s not as easy to find a bargain at the courthouse steps, Mr. Hale said. Lenders are present, and they’re seeking the amount owed on the property. Buyers can find better deals, as well as security, through a real estate agent, he added.
Property auctions are another way to find foreclosure properties, though it will likely take more time to close the transaction.
It’s worth it, however, because the auctions provide huge savings without financial surprises, such as back taxes, Roth said.
Buyers should still visit the property in advance to know what they’re bidding on, she said.
Banks or Mortgage companies might decide not to auction homes in their possession, which are referred to as real estate owned property, or REOs.
Instead, they ask real estate companies to list the properties in the multiple-listing service, as though they were normal vacant homes.
Houses that don’t sell on the courthouse steps are also added to this database, making the property available to all licensed real estate agents in the area, Tindall said.
In addition, deals are available with financing, Rasch said. Through an offer with the U.S. Department of Housing of Urban Development, her family was able to put only $100 down and use the down payment money to reduce the interest rate. The deal was available because the home was a foreclosure property, she said.
Rasch said they found their home at a good time; she has a toddler.
“Without this, we’d still be cramped in with my parents,” she said.
Copyright © 2009, The Augusta Chronicle, Ga. Distributed by McClatchy-Tribune Information Services.
Monday, January 19, 2009
Square Footage Reduced During Recession!


WASHINGTON – Jan. 19, 2009 –
The American dream is shrinking. For the first time in at least a decade, builders are substantially reducing the size of new houses.“We’re trending toward smaller homes,” says Gopal Ahluwalia, director of research for the National Association of Home Builders. He says growth in the average size of new single-family homes, which went from 1,750 square feet in 1978 to 2,479 in 2007, is starting to reverse. His analysis of Census data shows that homes started in the third quarter of 2008 averaged 2,438 square feet, down from 2,629 square feet in the second quarter. Ahluwalia, who began the quarterly analysis in 1999, says there have been slight dips before, but the latest drop was much steeper and is likely to hold even after the economy recovers.In a survey of builders this month, his group found that 89 percent are building or planning smaller homes than they had been. Kermit Baker, chief economist of the American Institute of Architects (AIA), also sees the shift toward smaller houses. He says it was obvious with high-end buyers even before the economic downturn and he expects it to continue with them. In a survey last April, the AIA found twice as many architects reporting a size decline rather than an increase. In 2006, the reverse was true. “Affordability is a major problem,” Ahluwalia says, and building smaller usually means cheaper. Also, he says, people are realizing as household size shrinks that they don’t need big homes. Baker says there is less incentive to buy a bigger, more expensive home as the economy weakens, home prices fall and energy costs remain a concern. He says people are less likely to see a bigger home as a good investment. Even high-end buyers, Baker says, are showing more interest in smaller, better-crafted homes.“People don’t want to be wasteful,” says JD Callander of Weichert Realtors. She says they are concerned about utility costs and cleaning requirements. Clients used to like the status of a big home, she says, but “those days are gone.”
Copyright © 2009 USA TODAY, a division of Gannett Co. Inc., Wendy Koch
Sales Up Year Over Year!
Well, here is some encouraging news in the marketplace! Year over year sales from December 2007 through December 2008 in all of Hillsborough County rose 18% according to the Greater Tampa Association of Realtors. In the Brandon area, which includes all of the Riverview area, overall sales rose almost 6%. While prices have continued to drop, the number of homes being sold has increased, bringing the inventory down. The average days on the market decreased slightly from 111 days to 110 days. The Brandon area days on market went from 109 to 98. Today is a good day to buy a home!
Thursday, January 15, 2009
Shadow Run, A Community With Acre Plus Lots!


Shadow Run is a community of custom built homes on acre or more lots. Located close to highways, shopping and schools, this community gives you a sence of country while being close-in. The commute to Tampa is quick as are the commutes to Sarasota and St, Petersburg. Homes vary isn size, from around 1900sf on the small end to quite large executive homes. Homes vary in age, with some being built in the late 1970's all the way up to 2008! Many have pools and many have nice upgrades.
Hurricane Forecast
UF: GAINESVILLE, Fla. – Jan. 15, 2009 –
Judging by the latest hurricane forecasts, Florida residents might want to add upgrading their roofs and checking the strength of their garage doors to their lists of New Year’s resolutions.Kurt Gurley, a University of Florida (UF) associate professor of civil and coastal engineering who conducts research on home vulnerability during hurricanes, says homeowners should take advantage of the five months before hurricane season to evaluate their homes, especially if the houses are at least 15 or 20 years old.“Essentially, the rule of thumb, which is not always exact, is the older the home that you live in, the more likely it is that you’re going to want to have some kind of evaluation performed,” Gurley says.Florida residents may have even more reason than usual to be concerned after hurricane forecasters at Colorado State University predicted 14 named storms in the 2009 season, including seven hurricanes – three of them major. The 2008 season saw above-average activity, with 16 named storms and eight hurricanes.Hurricane season starts June 1 and continues until Nov. 30.Gurley said Florida homeowners should consider redoing their roofs if their homes have old shingles. They should also check the braces on the garage door and the connections between the roof and walls. If the roof needs new shingles, consider installing a secondary water barrier on the seams below the shingles. Even if the shingles come off in a hurricane, the extra barrier will help keep water from seeping into the home.Gurley suggests visiting the Web sites of the Federal Alliance for Safe Homes (http://www.flash.org), a nonprofit organization, and the Institute for Business and Home Safety (http://www.disastersafety.org) for more tips on evaluating a house.Gurley says research teams at UF are working with the home-building industry and the Florida Building Commission, which recommends changes to the state’s building code, to determine the most cost-effective improvements to home building in Florida.“It’s pretty easy on paper to design a hurricane-proof home, but it’s going to cost a lot of money if the sky’s the limit,” Gurley says
.© 2009 FLORIDA ASSOCIATION OF REALTORS®
Judging by the latest hurricane forecasts, Florida residents might want to add upgrading their roofs and checking the strength of their garage doors to their lists of New Year’s resolutions.Kurt Gurley, a University of Florida (UF) associate professor of civil and coastal engineering who conducts research on home vulnerability during hurricanes, says homeowners should take advantage of the five months before hurricane season to evaluate their homes, especially if the houses are at least 15 or 20 years old.“Essentially, the rule of thumb, which is not always exact, is the older the home that you live in, the more likely it is that you’re going to want to have some kind of evaluation performed,” Gurley says.Florida residents may have even more reason than usual to be concerned after hurricane forecasters at Colorado State University predicted 14 named storms in the 2009 season, including seven hurricanes – three of them major. The 2008 season saw above-average activity, with 16 named storms and eight hurricanes.Hurricane season starts June 1 and continues until Nov. 30.Gurley said Florida homeowners should consider redoing their roofs if their homes have old shingles. They should also check the braces on the garage door and the connections between the roof and walls. If the roof needs new shingles, consider installing a secondary water barrier on the seams below the shingles. Even if the shingles come off in a hurricane, the extra barrier will help keep water from seeping into the home.Gurley suggests visiting the Web sites of the Federal Alliance for Safe Homes (http://www.flash.org), a nonprofit organization, and the Institute for Business and Home Safety (http://www.disastersafety.org) for more tips on evaluating a house.Gurley says research teams at UF are working with the home-building industry and the Florida Building Commission, which recommends changes to the state’s building code, to determine the most cost-effective improvements to home building in Florida.“It’s pretty easy on paper to design a hurricane-proof home, but it’s going to cost a lot of money if the sky’s the limit,” Gurley says
.© 2009 FLORIDA ASSOCIATION OF REALTORS®
Riverview's Military Connection!


The Riverview area (including Brandon, Valrico, Apollo Beach, Gibsonton, Bloomingdale) has a rich history of housing many of America's Military Personnel! The limit of on-base housing and the higher prices of homes in the immediate South Tampa area along with the convenience of travel on the Crosstown Expressway makes our area very desirable to those at MacDill. I provided a link to the base newspaper and also to military.com on the right. So if you are already here or are soon to arrive, you can get a sense of what is happening on base and in the surrounding area. I would also like to add my sincere gratitude and thanks to all of you who are currently serving or have served this great country!
Wednesday, January 14, 2009
Fear You Can't Qualify For Loan? Worth A Try!
ORLANDO, Fla. – Jan. 14, 2009 – Qualifying for a mortgage is not nearly as easy these days as it was just a couple of years ago, before the subprime-loan-market collapse and the worldwide credit freeze. Still, mortgages are approved every day, even for homebuyers with less-than-sterling credit records.“If you have over a 580 [credit] score, you have a chance” of qualifying for a home loan, said Marie Martin, a veteran broker with Mortgage Crafters in Brevard County. “A 600 score is better, and 620 and over is very good. You shouldn’t have a problem.”Consumers can get copies of their credit reports from each of the three major reporting companies at no charge at least once a year, but your credit score – a single number that typically ranges from a low of 300 to a high of 850 – will cost you $5 to $10 under most circumstances.Before seeking a mortgage, get a copy of your credit reports to check for inaccuracies and to gauge just how much information and detail – good or bad – your borrowing record contains. A consumer whose credit score is a little too low to qualify for a home loan may need a year or two, or more, to establish an improved track record.These days, a larger share of the loans being made are insured by the Federal Housing Administration, Martin said, and they allow down payments as low as 3.5 percent for qualifying buyers. Private lenders still make these FHA loans, but the government agency backs them for borrowers who meet its guidelines. The FHA has a variety of tools for helping homebuyers learn how to qualify for a mortgage, available online or by calling 1-800-CALL-FHA (1-800-225-5342).With housing prices down 25 percent in the past year alone and interest rates lower than they have been in decades, more people can qualify for a home loan based on their ability to meet the monthly payment, at least on paper. For those who think they are ready financially, who expect to remain put for several years and who want to own a home, here are some suggestions from industry professionals and the U.S. Department of Housing and Urban Development that may improve your odds of getting a mortgage:• Don’t assume you won’t qualify. Do some basic research on how to buy a home at the local library and on the Internet. The FHA has a handy Self Assessment Tool Kit to help prepare for homeownership; it’s at http://fhaoutreach.gov/FHASelf. • Document your history as a reliable tenant. At least one or two years’ worth of canceled rent checks or receipts showing a consistently good payment record is helpful.• Make an appointment to sit down with a local mortgage broker or lender. Get a professional to review the details of your personal situation. They will usually do a free qualification analysis in hopes of getting your business. They can identify problem areas that may be correctable.• If you use a mortgage broker, make sure he or she is in good standing with state regulators. Mortgage brokers represent multiple lenders and can help you find the best deals. But they also charge a fee, which is included in the loan. When choosing among brokers, check their state licenses with the Florida Office of Financial Regulation. You can do it online at tinyurl.com/749lgf. Copyright © 2009 The Orlando Sentinel, Fla., Jerry W. Jackson. Distributed by McClatchy-Tribune Information Services.
Tampa Bay Area Still Desirable!

STILL GOT IT
Two Florida cities remain in the top 10 of Relocation.com's list of desirable cities. Relocation.com analyzed cities' popularity to people wishing to relocate, and based the list on the number of requests it gets for information. On a per-capita basis for cities with more than 1 million people, Las Vegas retained the top spot as the No. 1 destination for people looking to make a long distance state-to-state move in 2008, followed by Denver; Charlotte, N.C.; Phoenix/Mesa, Ariz.; Portland, Ore., Seattle; Orlando; Washington, D.C.; Atlanta; and Tampa Bay/St. Petersburg. On the bottom end, the company says that for every 100 people looking to move to Michigan, 210 wanted to move out. In Ohio, 150 people wanted to move out for every 100 who wanted to move in. Only California saw a year-to-year change in direction, with more people now hoping to move out than move in.
© 2009 FLORIDA ASSOCIATION OF REALTORS®
Tuesday, January 13, 2009
Habitat for Humanity SUPERBUILD 2009!

 HABITAT FOR HUMANITY OF HILLSBOROUGH COUNTY NEEDS YOUR HELP! Habitat plans to build 4 new homes between January 23 and 31 during SuperBuild 2009. To accomplish this goal, Habitat will need 120 volunteers per day! There is no charge to participate in SuperBuild 2009. You're invited to participate in this exciting event. Click the headline to volunteer to help! Also, Habitat needs help with meals for our volunteers each day, and you can help by making a monetary donation for SuperBuild 2009 meals or gift cards from Dunkin' Donuts, Little Caesar's, Pizza Hut, Publix, SweetBay or Walmart. For further information, please contact Yvonne or Kathy by calling the Habitat office at 813-239-2242.
Children's Miracle Network

RE/MAX is one of the largest real estate networks, and has partnered with Children’s Miracle Network since 1992. Since that time, RE/MAX has raised more than $85 million across North America, making them the second largest sponsor. The Miracle Home® program generates the most donations. A Miracle Home creates an opportunity for Sales Associates to make a donation to the Children's Miracle Network member hospital aligned with their office on behalf of each transaction. In addition, RE/MAX offices implement host tournaments, galas, or other fundraisers to support Children's Miracle Network. RE/MAX Associates generated more than $9.8 million in donations last year alone. Said Vinnie Tracey, President, RE/MAX International, Inc., "Our business is about more than just buying or selling homes. Our business is to care for families, and what better way to show that care and concern than to support Children's Miracle Network." Their marketing tag line, "Outstanding Agents. Outstanding Results," applies not only to real estate, but to helping kids as well.

When the brothers of Phi Kappa Theta chose Children's Miracle Network as their national philanthropy in 2000, they demonstrated their belief that brotherhood extends beyond the walls of the fraternity houses and member rosters. Support for Children's Miracle Network hospitals comes in the form of Miracle Balloon campaigns, sporting event tournaments and various other fund raising events.
I am proud to be affiliated with these two great organizations who make it a priority to give back to the community. I make it a point to donate a portion of each transaction to Children's Miracle Network through my affiliation with RE/MAX.
Monday, January 12, 2009
Commercial Lot in Tampa!
 Wonderful 1.5 acre parcel on heavily travelled US41 (50th St.) in Tampa. Phase 1 and Phase 2 have already been completed, so a lot of time has been saved. Commuters from the Riverview area use this route to get into Tampa. Many others from the South Shore area use it as well. Potential traffic is great. This is a great buy at $225,000.

Tampa, Riverbend Charmer!
This charming 1156sf 2BR home sits on a lovely one-third acre lot in the Riverbend neighborhood in Tampa.

 The home has hardwood flooring in most areas, with ceramic tile in others.
 The home has a huge, semi-private deck off the rear of the home.
 Great home to commute to downtown Tampa or MacDill. The home has just been reduced to $150,000 which is below market value. This is a "short sale" situation. Come and view this home and make it yours! Click on the title of the post and it will take you to the visual tour of this lovely home.
sits on a lovely one-third acre lot in the Riverbend neighborhood in Tampa. The home has hardwood flooring in most areas, with ceramic tile in others. The home has a huge, semi-private deck off the rear of the home. Great home to commute to downtown Tampa or MacDill. The home has just been reduced to $150,000 which is below market value. This is a "short sale" situation. Come and view this home and make it yours! Click on the title of the post and it will take you to the visual tour of this lovely home.Saturday, January 10, 2009
A Little Info About Myself!
I thought I would take a little time to introduce myself. My name is Mike. I am originally from Chicago and moved to the Tampa area in 2000. I settled in the Riverview area because of housing values. You could get more bang for your buck here than in other parts of Hillsborough County. I am most pleased with that decision. The area definitely feels like HOME!
I became a Realtor in 2004 and loved it. I did not have the sphere of influence that established agents had, but managed to get busy pretty quickly. I have clients all over Hillsborough County and Pinellas County. Each year I have improved my business and each year has been better than the previous. That takes into account the very GOOD years and now the very BAD ones! It just goes to show that people are purchasing homes in all markets. I have been a multi-million dollar producer each year.
I joined RE/MAX South Shore Realty in January of 2008 and just celebrated my first anniversary there. I work with wonderful agents and the Brokers, Ed and Bonnie Pichette, could not be any better! I donate part of each tranasction to Chilren's Miracle Network, a partner of RE/MAX.
I love to play volleyball and you can find me at the local YMCA playing several nights a week. I also volunteer my time coaching volleyball to young teens at the YMCA. This past December, I was fortunate enough to assist former Olympic Volleyballer Keba Phipps (1988, 2004) in a 27 hour clinic for these same girls at the YMCA. What a fun time THAT was! I cannot wait for the next one!
I also love to work in the garden. Call it therapy. I tried my luck with roses, but they all died, much to the dismay of the neighbor who is a rose EXPERT. I try to use a lot of Florida native plants in the garden and conserve water whenever possible. In fact, everything in the garden is now surviving on what Mother Nature gives them. It is always a work in progress, so there is always something to do.
In college, I was a swimmer and a cheerleader and would have played volleyball if there was a team. I support the Truman State swimmers (Women are Defending National Champs) and volleyballers (4th in Nation) and have gone to see the swimmers a couple times when they visit Tampa during their holiday break. I believe it is important to give back.... I also support the volleyball team, just because of my love for the sport. I am also a member of Phi Kappa Theta Fraternity and try to be as active as possible.
I am currently a member of the Tampa Bay Business Guild, Greater Tampa Assoc. of Realtors, Florida Assoc. of Realtors, National Assoc. of Realtors along with other organizations.
I would like to present to you in the blog, a realistic portrayal of the Riverview, Florida area market and statistics to help you make a good decision whether you are in the market to purchase or in the market to list and sell your property. I can assist you with either and look forward to the time I can. If you have any questions, let me know... just email me or leave a comment..... I'd love to hear from you all.
Here's to a great 2009!
Mike
I became a Realtor in 2004 and loved it. I did not have the sphere of influence that established agents had, but managed to get busy pretty quickly. I have clients all over Hillsborough County and Pinellas County. Each year I have improved my business and each year has been better than the previous. That takes into account the very GOOD years and now the very BAD ones! It just goes to show that people are purchasing homes in all markets. I have been a multi-million dollar producer each year.
I joined RE/MAX South Shore Realty in January of 2008 and just celebrated my first anniversary there. I work with wonderful agents and the Brokers, Ed and Bonnie Pichette, could not be any better! I donate part of each tranasction to Chilren's Miracle Network, a partner of RE/MAX.
I love to play volleyball and you can find me at the local YMCA playing several nights a week. I also volunteer my time coaching volleyball to young teens at the YMCA. This past December, I was fortunate enough to assist former Olympic Volleyballer Keba Phipps (1988, 2004) in a 27 hour clinic for these same girls at the YMCA. What a fun time THAT was! I cannot wait for the next one!
I also love to work in the garden. Call it therapy. I tried my luck with roses, but they all died, much to the dismay of the neighbor who is a rose EXPERT. I try to use a lot of Florida native plants in the garden and conserve water whenever possible. In fact, everything in the garden is now surviving on what Mother Nature gives them. It is always a work in progress, so there is always something to do.
In college, I was a swimmer and a cheerleader and would have played volleyball if there was a team. I support the Truman State swimmers (Women are Defending National Champs) and volleyballers (4th in Nation) and have gone to see the swimmers a couple times when they visit Tampa during their holiday break. I believe it is important to give back.... I also support the volleyball team, just because of my love for the sport. I am also a member of Phi Kappa Theta Fraternity and try to be as active as possible.
I am currently a member of the Tampa Bay Business Guild, Greater Tampa Assoc. of Realtors, Florida Assoc. of Realtors, National Assoc. of Realtors along with other organizations.
I would like to present to you in the blog, a realistic portrayal of the Riverview, Florida area market and statistics to help you make a good decision whether you are in the market to purchase or in the market to list and sell your property. I can assist you with either and look forward to the time I can. If you have any questions, let me know... just email me or leave a comment..... I'd love to hear from you all.
Here's to a great 2009!
Mike
Subscribe to:
Posts (Atom)